
TFSA South Africa 2026: Complete Guide to Tax-Free Savings Accounts
The annual TFSA limit jumped from R36,000 to R46,000 from 1 March 2026 — a 28% increase. Here is everything you need to know about how tax-free savings accounts work, what the limits are, and how to use your TFSA effectively in 2026/2027.
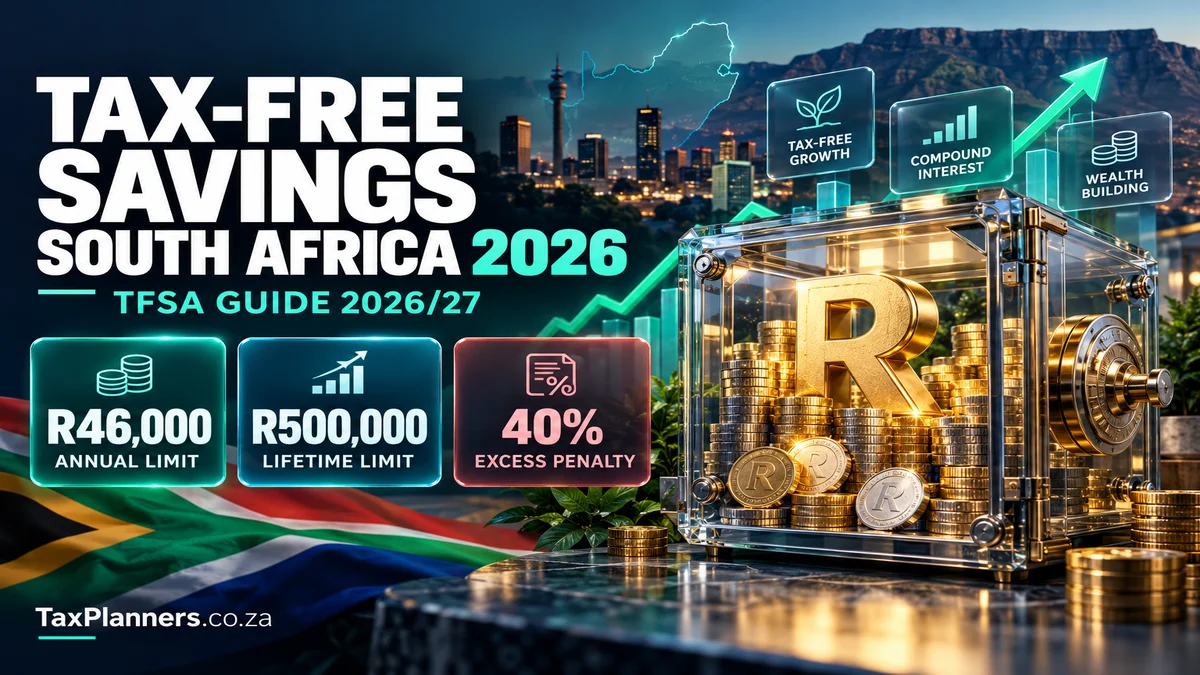
A tax-free savings account (TFSA) lets you contribute up to R46,000 per year (R500,000 over your lifetime) with no income tax, dividends tax or capital gains tax on returns earned inside the account. The R500,000 limit applies to your contributions only — investment growth can take your account value above this amount without any penalty. You can withdraw at any time, but withdrawals do not restore your contribution room. Excess contributions attract a 40% penalty tax.
What Is a TFSA?
A tax-free savings account (TFSA) is a registered savings or investment account offered by approved South African financial institutions under the Income Tax Act. Returns earned inside a TFSA — whether interest, dividends or capital gains — are completely exempt from tax. You pay no income tax on interest, no dividends tax on dividends, and no capital gains tax when you sell assets held inside the account.
TFSAs were introduced in South Africa in March 2015. The government created them to encourage long-term household savings and to give ordinary South Africans access to a simple, tax-efficient savings vehicle.
Approved TFSA products include fixed deposits, unit trusts, exchange-traded funds (ETFs), linked investment service provider (LISP) accounts, and retail savings bonds. The product type affects your investment returns but not the tax treatment — all approved products benefit from the same TFSA tax exemption.
Official source: SARS — Tax-Free Investments
2026/2027 Contribution Limits & History
The 2026 National Budget increased the annual TFSA contribution limit by 28% — the largest single increase since TFSAs were introduced. The increase is effective from 1 March 2026 (the start of the 2027 year of assessment).
| Year of Assessment | Annual Limit | Lifetime Limit | Change |
|---|---|---|---|
| 2016–2017 | R30,000 | R500,000 | Introduced |
| 2018–2020 | R33,000 | R500,000 | +R3,000 |
| 2021–2026 | R36,000 | R500,000 | +R3,000 |
| 2027 (from 1 Mar 2026) | R46,000 NEW | R500,000 | +R10,000 |
The R500,000 lifetime limit applies to the total amount you contribute to your TFSA — not to your account value. If your contributions total R500,000 and your investments grow to R800,000 or more, that growth does not breach the limit and attracts no penalty. Once the lifetime contribution limit is reached, no further contributions are permitted regardless of the annual limit, but your existing investments can continue to grow tax-free indefinitely.
Official source: National Treasury — 2026 Budget Review (Tax Proposals)
How a TFSA Works
When you open a TFSA with an approved provider, all returns generated inside the account are sheltered from tax:
| Return Type | Ordinary Account | TFSA |
|---|---|---|
| Interest income | Taxed at marginal rate (above annual exemption) | ✓ Exempt |
| Dividends | Dividends tax at 20% | ✓ Exempt |
| Capital gains | CGT at marginal rate × inclusion rate | ✓ Exempt |
| Contributions | Not limited | R46,000/yr; R500,000 lifetime (contributions only) |
| Withdrawals | Not restricted | Permitted; do NOT restore contribution room |
| Account value above R500,000 | N/A | ✓ Permitted — investment growth not limited |
The compounding effect of tax-free growth over time is significant, particularly for equity-based TFSAs. A R46,000 annual contribution growing at 10% per year generates meaningfully more wealth inside a TFSA than the same contribution in a taxable account over a 20-year period.
Who Can Open a TFSA?
Any South African resident individual may open a tax-free savings account. There is no minimum age requirement — minor children can hold TFSAs. However:
- Each person has their own annual and lifetime limits, independent of their parents or spouse.
- A parent may contribute to a minor child’s TFSA, but those contributions count against the child’s lifetime limit, not the parent’s. This is permanent — the child’s lifetime room used does not reset when they reach adulthood.
- Non-residents are generally not eligible.
- Trusts, companies and other legal entities cannot hold TFSAs — the account must be in an individual’s name.
You can open a TFSA with banks, unit trust companies, long-term insurers, stockbrokers, and other FSCA-licensed providers approved by SARS.
The 40% Excess Contribution Penalty
If your total contributions to all TFSA accounts in a year of assessment exceed R46,000, or your cumulative lifetime contributions exceed R500,000, SARS levies a 40% penalty tax on the excess contribution amount. This is one of the most important rules to understand about TFSAs.
The 40% penalty applies in every year of assessment that the annual or lifetime contribution limit is breached — it is not a one-time charge. If you contribute R56,000 in the 2027 year of assessment (R10,000 over the R46,000 limit), SARS levies a penalty of R4,000 (40% × R10,000) for that year. The excess amount is not removed from your TFSA automatically — you need to withdraw it and notify SARS.
| Scenario | Contribution | Excess | 40% Penalty |
|---|---|---|---|
| One provider, over annual limit | R56,000 | R10,000 | R4,000 |
| Two providers, combined over annual limit | R30,000 + R20,000 = R50,000 | R4,000 | R1,600 |
| Lifetime contribution limit reached, then further contribution | R500,000 cumulative + R20,000 new | R20,000 | R8,000 |
If you hold TFSAs with multiple providers, SARS aggregates your contributions. Your providers report contributions to SARS — you can view your cumulative TFSA contributions on your SARS eFiling profile. Check this regularly, especially if you have more than one TFSA account.
Withdrawals: The Key Rule to Understand
You can withdraw from your TFSA at any time, subject to your product provider’s terms. However, there is one critical rule that many TFSA holders misunderstand:
Unlike the Canadian TFSA, South Africa’s TFSA does not give back contribution room when you withdraw. If you have contributed R460,000 to date and then withdraw R50,000, your contribution room used remains R460,000. Re-contributing after a withdrawal counts as a new contribution against your remaining lifetime allowance of R40,000 — not against the withdrawn amount. This is permanent and cannot be reversed.
This makes the TFSA most valuable as a long-term savings vehicle. Frequent withdrawals and re-contributions erode your lifetime contribution room permanently.
TFSA vs Retirement Annuity: Which Is Better?
Both TFSAs and retirement annuities (RAs) offer tax advantages, but they work very differently. The right choice depends on your age, income, and goals:
| Feature | TFSA | Retirement Annuity (RA) |
|---|---|---|
| Tax on contributions | No deduction — contributions from after-tax income | Deductible up to 27.5% of taxable income (max R430,000/yr for 2027) |
| Tax on growth inside account | Fully exempt | Exempt |
| Tax on withdrawal | No tax on withdrawal | Taxed at retirement (lump sum tables; annuity income taxed at marginal rate) |
| Access before retirement | Anytime, subject to provider terms | Generally not before age 55. Under the two-pot retirement system (live since 1 September 2024), the savings component may be accessed once per tax year at any age, subject to fund rules and a minimum withdrawal amount. |
| Annual contribution limit | R46,000 | 27.5% of the higher of remuneration or taxable income, maximum R430,000/yr |
| Best for | Accessible savings, medium-term goals, tax-free wealth accumulation | Retirement-focused saving; high-income earners benefit most from the upfront tax deduction |
For many South African taxpayers, a combined approach works well: contribute to an RA to benefit from the upfront tax deduction at your marginal rate, then invest surplus savings into a TFSA for flexibility and tax-free growth. Higher-income earners generally benefit most from the RA deduction; younger savers or those on lower marginal rates often find the TFSA’s accessibility more valuable. This is a general illustration — consult a registered financial planner for advice suited to your circumstances. See our provisional tax guide for more on managing your annual tax efficiently.
TFSA Savings Calculator 2026/27
Use this calculator to project your TFSA value over time and check whether your planned contributions stay within the contribution limits. Investment returns shown are hypothetical illustrations only — actual returns depend on the product and market conditions and are not guaranteed.
📈 TFSA Growth & Limit Checker
Contributions are assumed to be made at the start of each year. The calculator applies the current R46,000 annual limit throughout — future limits may be adjusted by National Treasury. Investment returns are hypothetical and not guaranteed.
TFSA Strategy for 2026/2027
1. Top up to the new R46,000 limit as early as possible
If you were contributing R36,000 per year previously, you now have an additional R10,000 of annual contribution room. Contributing R10,000 per year at the start of each year, at a hypothetical 10% per annum, would grow to approximately R630,000 over 20 years (assuming contributions at the start of each year and a constant 10% return — actual returns will vary and are not guaranteed). Prioritise filling this new room early in the tax year (from 1 March 2026).
2. Check your cumulative contributions before contributing
Log in to SARS eFiling and check your cumulative TFSA contributions on your tax profile. If you have been contributing since 2015, your cumulative contributions may already be between R280,000 and R350,000 (depending on prior annual limits and whether you contributed the maximum each year). Knowing your remaining room prevents accidental over-contribution and the 40% penalty.
3. Consider opening a TFSA for your children
Minor children have their own R46,000 annual and R500,000 lifetime contribution limits. Contributing to a TFSA in a child’s name from an early age allows tax-free compounding over a long horizon. Keep in mind that contributions count permanently against the child’s lifetime limit — this room does not reset when they reach adulthood. This is a general illustration of the rules, not personal financial advice — consult a registered financial planner before implementing a strategy for a minor.
4. Do not withdraw unless necessary
Because withdrawals do not restore contribution room, every rand you take out of a TFSA and spend permanently reduces your lifetime tax-free savings capacity. If you need emergency funds, consider whether a separate accessible savings account would better preserve your TFSA contribution room.
5. Choose growth-oriented assets inside a TFSA
The greatest tax benefit inside a TFSA comes from high-growth assets — equity ETFs or unit trusts — because CGT and dividends tax exemptions compound over time. Low-return assets like a bank call account or fixed deposit provide a smaller tax advantage relative to the limited contribution room used. Consider reserving TFSA room for your longest-horizon, higher-return investments. This is a general principle — your optimal asset allocation depends on your individual circumstances and risk profile.
Frequently Asked Questions
What is the TFSA annual limit for 2026/2027?
What is the TFSA lifetime limit in South Africa?
What happens if I exceed the TFSA annual or lifetime limit?
Can I withdraw from my TFSA at any time?
Is interest on a TFSA taxable?
Who can open a TFSA in South Africa?
Does a TFSA count as part of my estate?
Can I have more than one TFSA?
Calculate Your Tax & Maximise Your Savings
Use our free South African tax tools to plan your 2026/2027 year.