
Income Tax South Africa 2026: SARS Calculator Guide
Updated 2026/2027 tax brackets, rebates, worked examples and free SARS-aligned calculators — everything you need to calculate your income tax correctly.
All rates, brackets and rebates sourced from the SARS official tax rates page and Budget 2026 documentation. Worked examples verified against the SARS tax tables.
What Is Income Tax and Who Must Pay It in South Africa?
South Africa operates a progressive tax system — the more you earn, the higher the percentage of tax you pay on the portion of income above each bracket. This ensures lower earners pay proportionally less than higher earners.
Who must register as a taxpayer and pay income tax:
- South African residents earning above the annual tax threshold
- Non-residents earning South Africa-sourced income
- Self-employed individuals with annual income above R30,000 from non-salary sources
- Employees whose employer deducts PAYE (Pay-As-You-Earn) monthly
- Companies and trusts operating in South Africa
- Individuals earning rental income, interest, dividends or freelance income
The current 2026/2027 tax year runs from 1 March 2026 to 28 February 2027. Individual tax returns are due between July and October/November 2026. For help with registration, see our SARS eFiling registration guide.
What Are the Income Tax Brackets for 2026/2027?
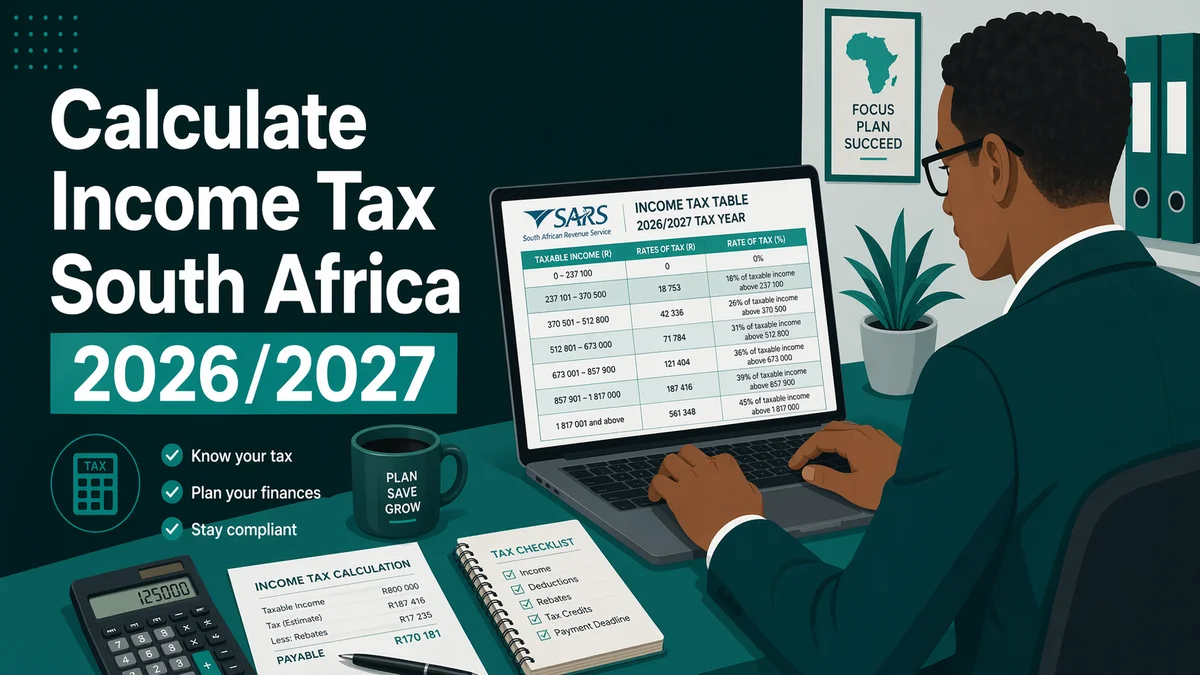
| Taxable Income (R) | Rate | Tax Formula |
|---|---|---|
| R0 – R245,100 | 18% | 18% of taxable income |
| R245,101 – R383,100 | 26% | R44,118 + 26% above R245,100 |
| R383,101 – R530,200 | 31% | R79,998 + 31% above R383,100 |
| R530,201 – R695,800 | 36% | R125,599 + 36% above R530,200 |
| R695,801 – R887,000 | 39% | R185,215 + 39% above R695,800 |
| R887,001 – R1,878,600 | 41% | R259,783 + 41% above R887,000 |
| R1,878,601 and above | 45% | R666,339 + 45% above R1,878,600 |
Source: SARS — Rates of Tax for Individuals. Tax year 1 March 2026 to 28 February 2027.
What Are the Tax Rebates and Tax-Free Thresholds for 2026?
Rebates are not deductions — they directly reduce the tax you owe after applying the bracket rates. The primary rebate of R17,820 divided by the 18% entry rate equals R99,000, which is why the tax-free threshold is that amount. If your calculated tax is less than R17,820, you pay nothing.
Medical aid tax credits further reduce your tax liability after rebates are applied:
- R364/month for the main medical aid member
- R364/month for the first dependent
- R246/month for each additional dependent
A family of four on medical aid (main member + 3 dependents) saves R364 + R364 + R246 + R246 = R1,220/month (R14,640/year) in direct tax credits, regardless of income level.
How Do You Calculate Your Income Tax Step by Step?
The 4-step calculation process:
- 1Calculate Gross IncomeAdd all income sources: salary, bonuses, rental income, freelance earnings, interest and dividends, foreign income and pension payments.
- 2Subtract Allowable DeductionsDeduct retirement fund contributions (up to 27.5% or R350,000), qualifying travel expenses, home office costs and PBO donations (up to 10% of taxable income). This gives you Taxable Income.
- 3Apply the Tax TableFind your bracket. Use the base tax figure and add the marginal rate on income above the bracket floor. This gives Tax Before Rebates.
- 4Deduct Rebates and Medical CreditsSubtract your age-based rebate (R17,820 for under 65) and monthly medical aid tax credits. The result is your annual tax liability.
Worked examples — 2026/2027 tax year, taxpayer under 65:
Band 2 — 26% marginal
Band 3 — 31% marginal
Band 6 — 41% marginal
What Deductions and Credits Can Reduce Your Tax?
| Deduction / Credit | Limit | Effect |
|---|---|---|
| Retirement fund contributions | 27.5% of taxable income or R350,000 | Reduces taxable income |
| Medical aid tax credits | R364/R364/R246 per month | Reduces tax directly |
| Travel allowance | Business km only, with logbook | Reduces taxable income |
| Home office expenses | Proportional % of home used | Reduces taxable income |
| PBO donations | Up to 10% of taxable income | Reduces taxable income |
| Tax-Free Savings (TFSA) | R36,000/year, R500,000 lifetime | Tax-free growth |
Travel allowances require a detailed logbook recording date, destination, purpose and kilometres for every business trip. Without a logbook, SARS disallows the claim. The prescribed rate for 2026 is approximately R4.84 per kilometre for business travel.
For more on PAYE tax rates across all income levels, see our SA tax brackets guide. For assets like property and shares, Capital Gains Tax (CGT) applies separately — see Section 8 for details.
How Does PAYE Work for Salaried Employees?
- 1Employer calculates annual expected incomeYour employer multiplies your monthly salary by 12 and adds any expected bonuses and allowances to get your projected annual taxable income.
- 2Tax is calculated using SARS tablesThe employer applies the 2026/2027 tax bracket formula, deducts the primary rebate, and divides by 12 to get your monthly PAYE deduction.
- 3PAYE is paid to SARS monthlyYour employer submits the deducted PAYE to SARS by the 7th of the following month. Your payslip shows gross salary, PAYE deducted and net take-home pay.
- 4IRP5 issued at tax year-endAfter 28 February each year, your employer issues an IRP5 certificate showing total remuneration, PAYE deducted, retirement contributions and medical aid. This is your primary document for filing your annual tax return.
If you changed jobs mid-year, received a large bonus, or had significant deductions your employer did not account for, your PAYE may be over- or under-deducted. Filing your annual return reconciles this — if SARS owes you money, you get a refund.
Who Must Pay Provisional Tax in South Africa?
Who qualifies as a provisional taxpayer:
- Self-employed individuals and sole proprietors
- Company directors earning directors’ fees
- Freelancers with annual non-salary income above R30,000
- Rental property owners
- Investors earning significant interest, dividends or capital gains
- Individuals earning foreign income above the threshold
| Payment | Deadline | Basis |
|---|---|---|
| First provisional (IRP6) | Last business day of August | Estimated income for first 6 months |
| Second provisional (IRP6) | Last business day of February | Estimated full-year income |
| Voluntary third payment | With annual return (July–Jan) | Top-up to avoid interest |
If you underestimate your provisional tax by more than 20% of the actual tax assessed, SARS charges a 20% penalty plus interest. Estimate conservatively — it is better to overpay and receive a refund than to face penalties. For more on simplified tax options for small businesses, read our Turnover Tax South Africa guide.
How Can You Reduce Your Tax Bill Legally in South Africa?
- Max out retirement contributions: Contribute 27.5% of taxable income — at a R600,000 salary this saves roughly R33,000 in tax per year at the 36% marginal rate
- Use your TFSA allowance: R36,000 per year into a Tax-Free Savings Account grows tax-free — no CGT, no dividends tax, no interest tax on withdrawal
- Claim medical aid credits: Ensure all dependents are correctly registered on your plan — each dependent saves R364 or R246/month directly off your tax bill
- Keep a travel logbook: Business kilometres are deductible — without a logbook the claim is disallowed
- Donate to registered PBOs: Donations are deductible up to 10% of taxable income — at the 31% bracket, R10,000 donated saves R3,100 in tax
- Defer income to a lower-earning year: If possible, shift bonuses or project income to a tax year where you expect lower overall earnings
Cryptocurrency is treated as an asset by SARS — profits from trading are taxed as income, and investment gains are subject to Capital Gains Tax. All crypto transactions must be declared. See our Crypto Tax South Africa guide for full details.
How Do You File Your Tax Return on SARS eFiling?
- 1Gather your documentsIRP5 from employer, medical aid certificate, retirement annuity certificate, investment statements (IT3b for interest, IT3c for dividends), travel logbook if claiming travel allowance.
- 2Log into eFiling and open your returnGo to sarsefiling.co.za, navigate to Returns → Returns History → File Return. SARS auto-populates data from third-party sources — verify each figure against your documents.
- 3Declare all income and claim deductionsAdd any income not in the auto-populated data — freelance income, rental income, foreign income, crypto gains. Then claim all eligible deductions: retirement contributions, travel expenses, home office costs, medical out-of-pocket expenses above the credit threshold.
- 4Review, submit and check your assessmentReview every field carefully before submitting — errors trigger audits and delays. After submission, SARS issues an ITR12 assessment. Query any discrepancy within 30 business days using a Request for Correction (RFC).
When Do You Get a Tax Refund from SARS?
Common situations that result in a SARS refund:
- Your employer over-deducted PAYE during the year
- You changed jobs mid-year and tax was calculated incorrectly on IRP5s
- You claimed significant deductions (retirement, travel, home office) not factored into PAYE
- You made excess provisional tax payments
- You received a large medical out-of-pocket expense qualifying for additional credits
| Return Type | Refund Timeline |
|---|---|
| Auto-assessment (agreed) | 72 hours to 21 days |
| Standard self-filed return | 21 to 30 business days |
| Complex return or audit | Up to several months |
If your refund is delayed, possible causes are: outstanding returns from prior years, SARS verification or audit review, a tax debt being offset against the refund, or incorrect banking details on file. Check your refund status on eFiling under “Returns” → “Notices/Letters” or contact SARS directly on 0800 00 7277.
You can claim refunds for returns up to five years retrospectively — if you have unclaimed deductions from previous years, submit those returns promptly.